For a multi-generational trip, make an insurance checklist for every traveller before trying to buy one policy for the whole group. A common booking, surname or payer does not establish that everyone is insured on the same terms. Match the children, adults and older relatives to the actual proposed contract, then confirm any differences privately with the insurer.
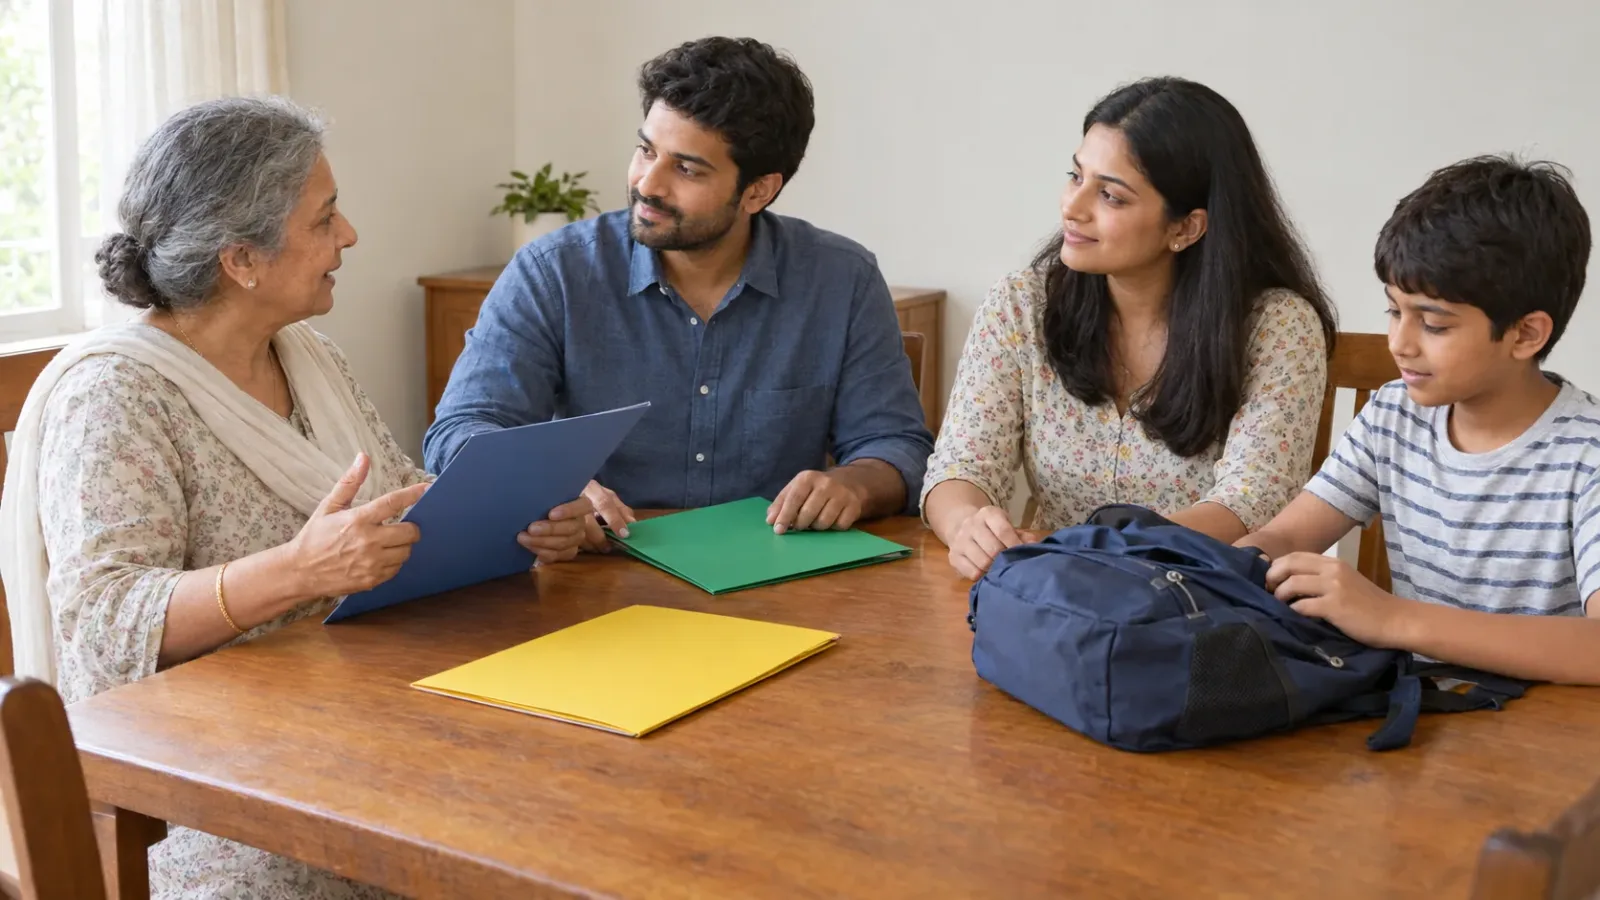
AI-generated fictional photograph of a family sorting plain travel folders at home. Not an insurer consultation, issued policy or real customer.
Start with one row per traveller
Record the traveller's correct name, date of birth, actual residence, journey dates, destinations and planned activities. Add the proposed insurer, exact product, plan, wording version, policy reference once issued and unresolved questions. If someone joins late or returns separately, their row must describe their own journey, not simply the group leader's dates.
Keep medical declarations and identity documents in the genuine private insurer channel, not a shared public sheet or a large holiday chat. A group coordinator can track whether a question is answered without collecting every person's private history. Agree who may help and who may receive documents.
Do not turn the word family into confirmed eligibility
HDFC ERGO's family-insurance page markets a family product, while its travel prospectus separates plan and eligibility categories. ICICI Lombard's travel page presents family and senior options. These are leads to the correct documents, not proof that a particular grandparent, child, adult sibling or non-travelling payer fits your quote.
Ask the insurer who can be included together, whether separate contracts are needed and how limits apply to each named person. Do not replace an ineligible person's residence or age to make a form proceed. A paid premium or a successful online quote is not a resolved answer to a mismatch.
Ask each person the same contract questions
For each proposed insured traveller, check:
- Is this exact person accepted for their actual residence, age, journey and trip status?
- Which benefits are selected, and when and where do they apply?
- Are limits individual, shared or subject to smaller benefit limits, deductibles or co-payments?
- What declarations and updates does the insurer require from this person?
- What is the assistance and claims route, including any approval or evidence process?
The questions are a checking method, not statements of current cover. Do not copy an older relative's answer to a child or assume the youngest traveller's eligibility settles the whole group.
Resolve health-cover questions without a group-wide promise
ICICI Lombard's family-purchase guide tells readers to check the treatment of a family member's pre-existing condition. Its Europe page and TripSecure+ brochure contain product marketing that must be matched to the actual wording and selected benefits. Do not read a broad headline as unconditional medical cover.
No person's medical cover, pre-existing-condition treatment, emergency exception, eligibility or fitness to travel is confirmed by this article. Relevant dated primary evidence establishing those answers for your proposed policies was not obtained. Ask the insurer for a written, person-specific answer tied to the exact contract; if an answer conflicts with the wording, ask it to settle the conflict before buying. Seek individual clinical advice separately where needed.
Test what happens when one person changes the group plan
If one traveller cannot go, returns early or needs a companion to stay, ask how each relevant policy treats that situation. Identify whose non-refundable costs are being discussed, who paid them, which insured relationship or event matters and what evidence is required. One person's problem does not automatically establish a payable claim for everyone.
Do the same for different return dates, separate bookings and optional activities. Ask about the actual benefit and traveller rather than assuming that a group tour or a shared booking reference connects all contracts. No cancellation, interruption, companion or activity claim is guaranteed here.
Finish with a private handover for each person
Open the issued schedule, wording and endorsements. Reconcile names, dates, destinations, selected benefits and written clarifications for each traveller. Do not mark the group complete while one person's correction is still open. Keep a small status list: confirmed document checked, insurer question open or correction requested.
Give each traveller and their agreed helper an accessible copy of the correct policy reference, assistance contacts and document location. Test offline access without relying on one coordinator's phone. Keep sensitive declarations separately; consent to help organise the trip is not blanket permission to circulate medical records.
Use the older-parent contract checklist for a deeper reading exercise, not as a Japan coverage rule. Ask on the trip-planning page about the actual tour inclusion. This article does not establish that TripKeeper sells policies, handles claims or collects health records.
Reviewed 14 November 2026 against six linked official insurer pages/documents. Relevant current revision dates were not established. Marketing descriptions and a public prospectus do not settle a person's offered contract. No premium, recommended policy, medical rule, visa requirement or claim outcome is confirmed.
A Miranda House graduate and lawyer who traded courtrooms for slow travel. Cheshta travels with the batches we host ourselves, with a soft spot for travelling alongside elders.
Planning your next trip?
We'll handle insurance, hotels, airport assistance and the itinerary — the same way we do it for every trip.
Questions on this article
asked by readers, answered by us
Was this helpful?
one tap, no sign-up